Preserve Wealth Group
Step 2 of 3

You just did something most people your age never do.

You asked what your savings could pay you every month. Here’s the real answer. Nine minutes, and I go through the reasons you might not want to do this.

Show Me My Number15 minutes. Costs nothing. Nothing to move, nothing to sign.

Someone from our team will call you today from (430) 206-1140. Or pick your own time above and we will call then instead.

Excellent5.0 on Trustpilot
Three things you can check yourself

Don’t take our word for any of this

You just watched a video from someone you found through a Facebook ad. Here is what other people have said about this, none of whom have anything to do with us.

Ben Bernanke
Ben BernankeChairman, US Federal Reserve, 2006–2014
01

The man who ran the Federal Reserve had two of them

Before Ben Bernanke could take the Fed chairmanship he had to publish his personal finances. He held relatively little in stocks and bonds. His two largest holdings were annuities.

Public financial disclosure, reported by USA Today, July 2008. Takes about a minute to look up.

RETIREMENT ACCOUNT STATEMENTYOUR BALANCE$500,000AS MONTHLY INCOME FOR LIFE$2,645 / moillustrative
US Department of LaborLifetime income illustrations, in force since 2021
02

The government changed your statement because of this

The Department of Labor now requires your retirement statement to show what your balance would pay you as monthly income for life, including a version that keeps paying your spouse. They changed the rule because a balance is not a plan.

US Department of Labor, lifetime income illustrations. Their own guidance: an annuity provides a steady stream of income that lasts throughout your life.

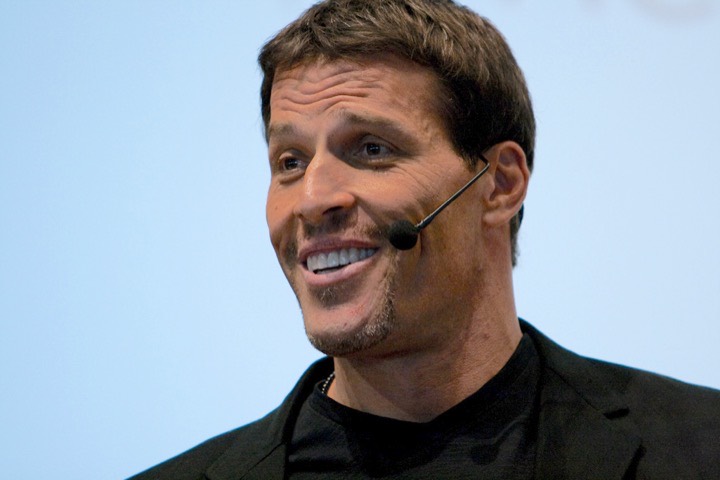
Tony Robbins
Tony RobbinsAuthor, Money Master the Game
03

There is a chapter about this in a book you have heard of

Tony Robbins wrote about this in Money Master the Game. Chapter 2.7 is called “Myth 7: I hate annuities, and you should too.” We are not going to summarise it for you, and we are not claiming he knows who we are.

Go and read it before your call if you want a second opinion that is not ours.

Wait, doesn’t Tony Robbins hate annuities?

No. That is the whole point of the chapter, and the title is the joke. It is written as a myth he is taking apart, not as his opinion. He came across an online advert that said “I hate annuities and you should too,” went and looked at who had paid for it, and found somebody selling their own stock picking for a fee. The chapter is him working out whether the criticism actually holds up.

Where he says the criticism is fair. Variable annuities. He is blunt about those. Mutual funds wrapped inside an insurance contract, fees stacked on fees, and he runs the arithmetic at roughly 4.7% a year all in. He tells you to avoid them. We do not place them either.

Where he lands. That there are annuities you should genuinely hate, and that lumping all of them together throws out a tool that has existed since Roman times. His line is that “not all annuities are created equal.”

Who he went and asked. Dr David Babbell, who taught investment at Wharton for over thirty years, ran research for the pension and insurance division at Goldman Sachs, and consulted for the US Treasury, the Federal Reserve and the Department of Labor. Babbell published his own personal retirement plan. He used income annuities. Robbins flew to Philadelphia for a one-hour interview with him that ran four hours.

He also points at Ben Bernanke’s financial disclosure, the same one above, and at Dr Jeffrey Brown, an advisor to the US Treasury and the World Bank who sat on the Social Security Advisory Board. Brown ran a study on how the same product is described. Presented as an investment, about one in five people found it attractive. Presented as income insurance that keeps paying you for as long as you live, more than seven in ten did.

And the honest part. He is not connected to us, he does not know we exist, and he is selling books. We are telling you the chapter is there because it is the easiest place to get a second opinion that is not ours. Read it and make your own call.

Money Master the Game, Tony Robbins, Chapter 2.7. Summarised here in our words. We are not reproducing the chapter and we do not have any arrangement with the author or the publisher.
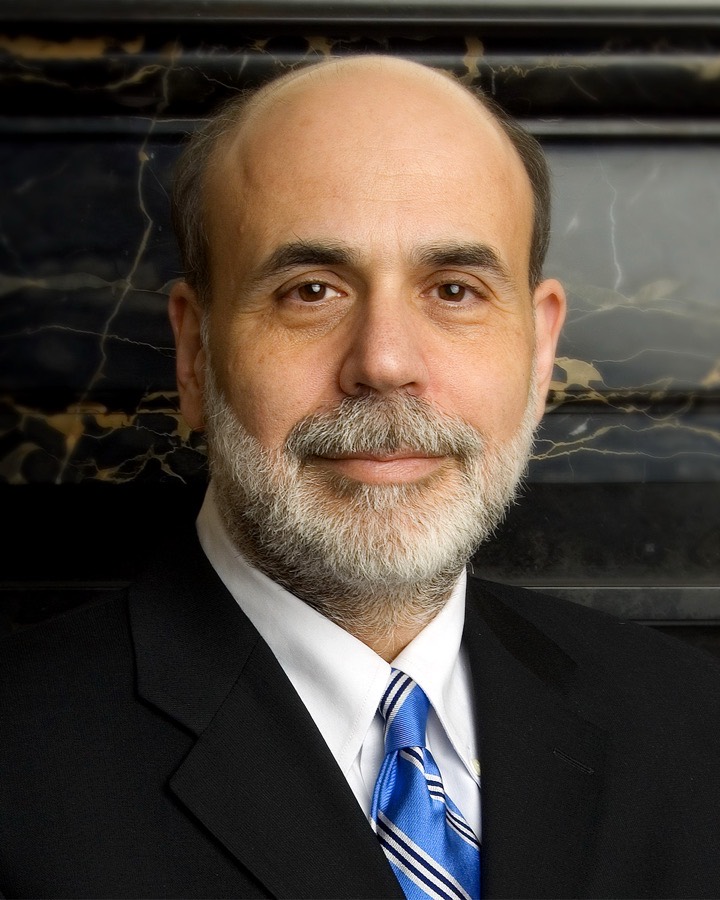
Ben Bernanke, official portrait, Board of Governors of the Federal Reserve System, public domain. Tony Robbins photograph by Randy Stewart, licensed under CC BY-SA 2.0. Neither is affiliated with Preserve Wealth Group, and neither has endorsed us or any product.

The math

Same money. Two very different paychecks.

Most people only ever get shown one of them.

If you have
Drawing it down
$0
per month
This is the amount the research says you can safely take out each year. And “safe” here means it worked about nine times out of ten. It is not a guarantee.
Guaranteed for life
$0
per month
Based on what insurance companies are quoting right now for a 65-year-old. Paid every month for as long as you live. Live to 101 and it is still showing up.

Same $500,000. Roughly double the monthly income, and it never runs out.

That second one is an annuity. A guaranteed income annuity, which is the simplest thing in the category. You hand over a defined amount. They pay you a defined amount every month for as long as you live.

These numbers use a 65-year-old man. And here’s the part that trips everybody up. Start younger and the monthly check is smaller, because it’s got to last longer. Start older and it’s bigger from day one.

So waiting looks like the smart play. Watch the video up top. I run the break-even on that, and it’s not what you’d think.

Your actual number comes down to your age, your state, and honestly which carrier’s paying best that week. That’s why a licensed professional runs it instead of a calculator.

The options

There’s three kinds. Most people get sold the wrong one.

Fixed

Grows at a set rate for a set number of years. Safe, predictable, and honestly pretty boring.

For: beats a CD, no market risk.

Income

You hand over part of your savings. They send you the same amount every month for the rest of your life. Nothing else pays you this much and guarantees it. The trade is you can’t get that part back.

For: you want the paycheck now or soon.

Indexed

Goes up when the market goes up, but only to a limit. When the market drops, you don’t lose anything. You can pay extra to lock in a guaranteed monthly check later on.

For: growth with a floor, income in 5–10 years.
Straight with you

The three catches. Before you talk to anybody.

Most people in this business give you the upside and let you find the rest out later. Here’s all of it now.

1

You can’t get it all back

Most of these let you take out about 10% a year with no penalty. The rest stays put for a set number of years. So if there is any chance you need that money for a new roof or a medical bill, it should not go in here. That is why this is never all of your savings. For most people it is a quarter to a third.

2

Your family inherits the account value, not the income number

Whatever is left in your account goes to the people you name. The insurance company does not keep it. But if you take an income rider you will be shown two figures, and they are not the same thing: the account value, and a guaranteed income base the monthly payment is worked out from. Your family gets the account value. It is the smaller of the two and it falls as you take withdrawals. Ask to see both, every year, before you decide anything.

3

The professional gets paid

If you go ahead, the insurance company pays them a commission. It comes out of the insurance company’s own money, not out of yours. So if you put in $500,000, your account starts at $500,000. It is still a reason to be careful. Ask them straight out what they make on it. A good one tells you the number without flinching.

Show Me My NumberYou'll hear all three again on the call, before anybody says a number.

This isn’t right for everybody

We’d rather tell you now than waste your time on a call.

Trustpilot

What licensed professionals say about working with us

CJ
Christian Jaehn-Kreibaum
5 reviews

Working well with Preserve Wealth Group

I have been working with Preserve Wealth Group for the past seven to eight months as a financial advisor licensed in both insurance and investments. Based on my experience with other organizations over the years, I have found Preserve Wealth Group to be exceptionally supportive and responsive. Their team is always willing to help, they continually introduce new tools and resources that enhance my ability to serve clients, and their back-office support is knowledgeable, communicative, and efficient.

Aug 4, 2026
SM
Simon Marples
3 reviews

I appreciate the Preserve Wealth Team

The management team at Preserve Wealth Group does a very good job of living up to their commitments. They are all working hard to create the success expected by myself and all the other members I've met. I appreciate their creativity and drive to maximize their commitment to ensure our success.

Oct 20, 2025
JT
Jerome Timmermann
1 review

I highly endorse Preserve Wealth Group

Just starting my 45th year of tax mitigation I remain fully active, which means seldom does a new impactful strategy or concept add to my capacity. Being a member now for 6 months, everything promised plus more has occurred.

Sep 2, 2025
ES
Elijah Sarge
1 review

Very high level advisors

Very high level advisors, that use incredible tax mitigation strategies, and teach others how to take control of your financial picture. I'm continually astounded on the strategy's this company uses.

Sep 2, 2025
KB
Kaleb Bowden
1 review

Phenomenal experience with the team

They not only provide on the value they bring but truly are getting the right connections in place to make impact in the lives of business owners across the country. Very rarely do you see people doing what they say they are going to do.

Aug 29, 2025
LO
Lou
4 reviews

Preserve Wealth Group does in fact Preserve wealth

Preserve Wealth Group works with the best advisors in the country and the community of advisors is amazing! I learned about money saving opportunities, as well money making opportunities that I didn't even realize existed nor did my CPA.

Aug 27, 2025
CL
Corbin Lindsey
2 reviews

Preserve Wealth Group is Amazing!

Preserve Wealth Group has outdone their competition by creating a platform for experienced and newer advisors to collaborate to ultimately help more clients reap the rewards of amazing tax strategies. This has been a great experience.

Aug 27, 2025

Pick your time

Fifteen minutes. Either way you’ll know more about your own situation than you do right now.

Pick a time below — takes about 20 seconds
No cost. Nothing to move. Nothing to sign.

What people ask before the call

Is somebody going to try to sell me?

Not on either call. Nobody can take your money over the phone and nobody's going to ask you to.

The 15 minutes decides whether this even fits your situation. If it does, you get introduced to a licensed professional in your state who runs your actual numbers. If it doesn't, we'll tell you on the call and you're done.

I've heard annuities are a rip-off.

Some of them are, and that's a fair criticism. There are annuities sold in this country you can't touch for twelve years. There are ones where the growth is capped so low you barely make anything. The professionals in our network don't use those.

But the word annuity covers as much ground as the word insurance. Car insurance and life insurance are both insurance and they have almost nothing to do with each other. The one most people should look at is the simplest one there is. You hand over an amount, they send you a check every month for the rest of your life. No limit on the growth. Nothing to keep track of. Judge that one on its own.

What if the insurance company goes under?

Three things protect you. First, the professionals in our network only use insurance companies rated A or better, ones that paid every claim through 2008 and through 2020. Second, your state makes those companies hold money in reserve behind every contract they sell, and they can't spend it on anything else. Third, every state runs a backup fund that covers you if an insurance company fails, usually up to somewhere between $250,000 and $300,000. If your amount is bigger than your state's limit, you split it between two companies and you're covered on both.

Now let me be plain about what this is not. It is not FDIC insured and it is not backed by the federal government. The insurance company owes you the money, with that state backup fund behind it. Anybody who tells you different is wrong.

How do you guys make money?

Preserve Wealth Group isn't an insurance company and we're not licensed to sell annuities. We match you with independent licensed professionals, and those professionals pay us for the introduction. You pay us nothing. Ever.

If you go ahead, the insurance company pays the professional a commission. It comes out of the insurance company's own money, not out of yours, so your account starts at the full amount you put in. That's still a reason to be careful, which is exactly why you should ask them what they make on it. A good one tells you the number without flinching.

How long is the first call?

Fifteen minutes, usually less. Four questions about your situation, then either an introduction or an honest no.

Do I need to have anything ready?

A rough idea of what you've got, and more importantly where it's sitting. An IRA, an old 401(k), a plan at the job you're still at, CDs, a brokerage account, an annuity you already own. That one detail decides which options are actually open to you, and knowing it up front saves most of the call.

Pick My Time